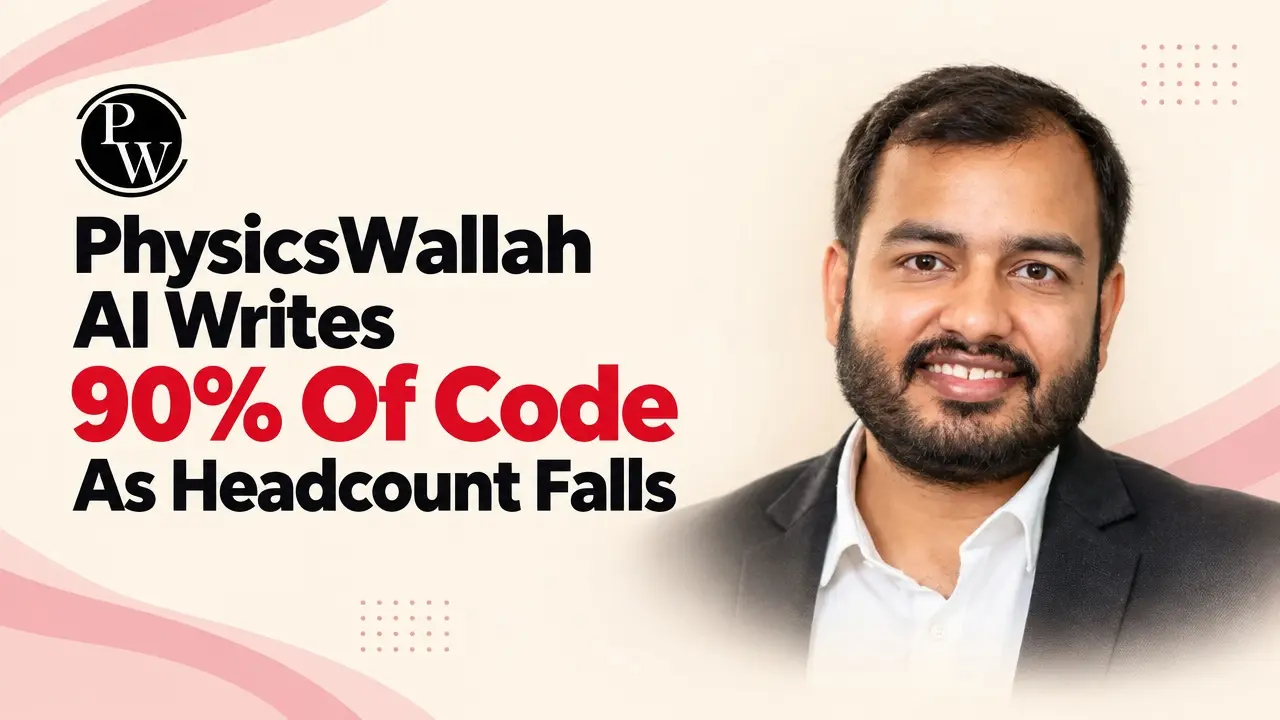

PhysicsWallah now lets artificial intelligence write about 90 per cent of its code, management told analysts on the 4 November earnings call, and the shift is showing up in the payroll. Employees fell from 19,567 in June to 19,104 in September, a net 463, the filings cited by Open magazine show. Net faculty fell by 151.
No split between layoffs and attrition has been published, and no rupee figure attaches to the savings. Management says AI carries more of the work in writing learning material, checking content, setting papers and grading answers. For a payroll of 19,104, that is the first time the efficiency claim has reached headcount itself.
Read more on newzshort:
Unacademy Founders Plan Rs 700 Crore AI And Deeptech Fund
What The September Quarter Delivered
The cost story sits on the strongest quarter of its short listed life. Consolidated revenue rose 18 per cent to Rs 1,242 crore, and profit after tax more than doubled to Rs 142 crore from Rs 70 crore. The first half swung to Rs 55 crore of profit from a Rs 57 crore loss.
Online carried it. First-half revenue there grew 29 per cent and the segment earned Rs 312 crore on pre-Ind AS EBITDA after Rs 13 crore of lease payments, the engine funding the classrooms.
Read more on newzshort:
Ather Energy Posts First Profit Of Rs 1.26 Crore
The Rs 131 Crore Rent Bill
Offline, which runs 370 centres including 167 Vidyapeeth sites, booked Rs 1,031 crore of first-half revenue and lost Rs 108 crore on pre-Ind AS EBITDA. The shareholder letter explains the gap: Rs 41 crore of segment EBITDA, less Rs 45 crore of shared costs, plus Rs 27 crore of stock compensation, less Rs 131 crore of rent. Rent is triple operating profit.
Improvement is real. Offline margin moved from minus 13 per cent to minus 10.5 per cent and the half-year loss narrowed from Rs 120 crore. In the quarter, revenue grew 9 per cent to Rs 541 crore while the loss widened to about Rs 8 crore from Rs 7 crore. Vidyapeeth took Rs 682 crore, two-thirds of offline revenue, on 2.53 lakh enrolments against 2.19 lakh.
Where The 463 Went
The faculty number hides more than it shows. PhysicsWallah had 84 more salaried teachers than in June, offset by 235 fewer consultants, so the full-time bench grew while net faculty fell 151. Headcount was still above last year.
Employee benefit expense excluding stock compensation rose from Rs 432 crore to Rs 482 crore in the quarter, and from Rs 847 crore to Rs 969 crore in the half. Its share of revenue fell, from about 41 per cent to 39 per cent, because revenue grew faster. Technology spend rose from Rs 70 crore to Rs 104 crore. The company is buying operating leverage, not a smaller cost base.
Growth Arithmetic And A $20 Million List
Revenue grew 21 per cent in the half against guidance of about 30 per cent for FY27, implying roughly 39 per cent in the second half. Some must come from deals. PhysicsWallah is in advanced talks with a couple of fully online education businesses and has earmarked under $20 million from the Rs 300 crore of IPO proceeds reserved for unidentified acquisitions, expected to add under 5 per cent of growth.
The build-out is slowing. After adding 50 Vidyapeeth centres in a year, it plans 25 to 30 a year, with fewer teachers hired ahead of admissions.
Risks, And 18 November
Three questions decide whether this is a turn or a good print. Can offline close a Rs 108 crore first-half gap in six months, with management expecting Vidyapeeth to break even this year? Does Tuto, the voice tutor that costs about Rs 17 an hour to deliver against Rs 300 to Rs 1,000 for a home tutor, sell, when the company expects little revenue from it this year? And can growth be bought without thinning margins?
The street is split. Prabhudas Lilladher reiterated accumulate with a Rs 140 target on 6 November, while Motilal Oswal carries a buy and Rs 200 from 8 October, both per Moneycontrol. Its first Investor Day falls on 18 November, the listing anniversary.
The editorial read: 463 will get the headlines, and it is the least informative number here. A 2.4 per cent sequential fall proves little, and the company does not dress it up as an AI saving. What the filings show is a business swapping people costs for technology costs while running classrooms whose rent exceeds their operating profit. If the second half delivers 30 per cent without new leases outrunning enrolments, AI is buying margin rather than trimming staff. Until then, this is a company getting better at what works, online, and still learning to make its biggest bet pay.