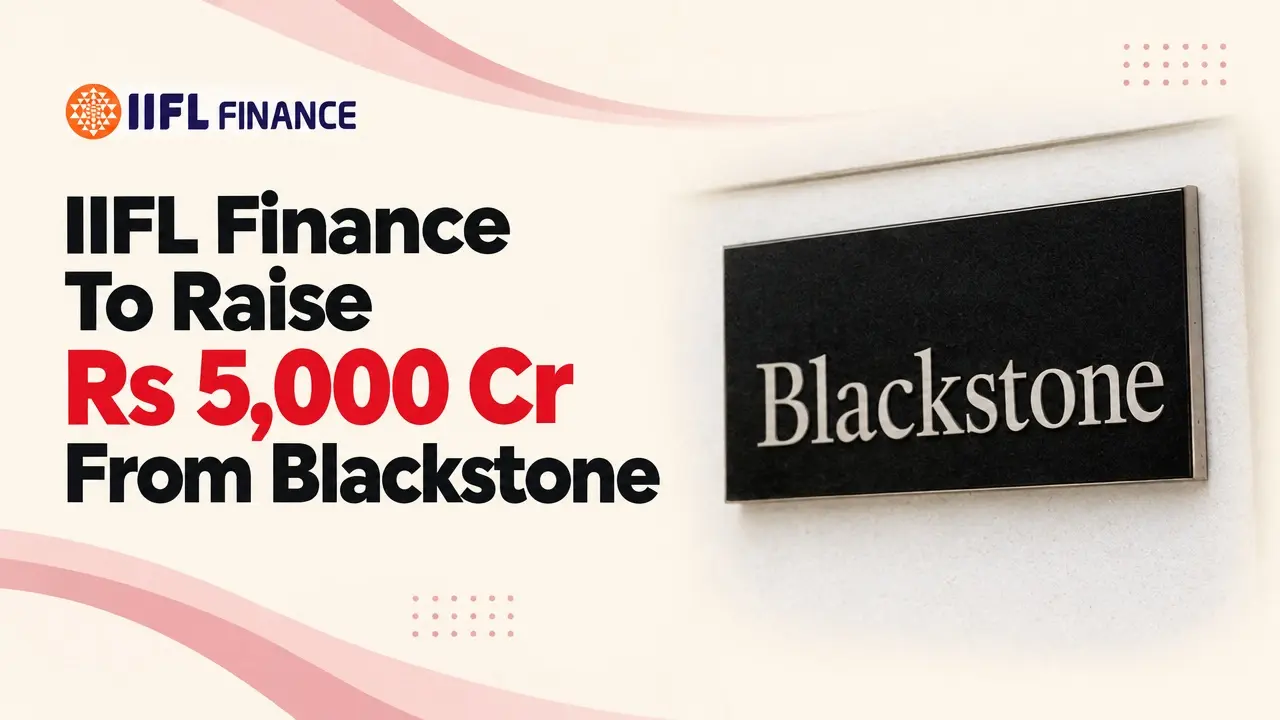

Blackstone is set to invest Rs 5,000 crore in IIFL Finance for a 15 per cent stake, with promoters Nirmal Jain and R Venkataraman putting in Rs 1,200 crore alongside, Business Standard reported on 10 November. The two cheques together take the capital raise to Rs 6,200 crore. The IIFL Finance board weighed proposals from Blackstone and rival buyout fund Advent before settling on the American alternative asset manager, The Economic Times reported on 9 November. The transaction still needs regulatory and shareholder clearances.
The raise answers a balance sheet problem, not a demand problem. IIFL Finance grew its loan book 38 per cent in the first half of FY27, with 90 per cent of the book secured, according to its investor presentation. An NBFC expanding assets at that pace has to fund them with borrowings, and borrowings can be levered only so far before capital adequacy and rating agencies push back. Fresh equity buys the next leg of growth without stretching leverage.
Read more on newzshort:
MobiKwik Wins RBI NBFC Licence, Targets Rs 5,000 Crore
What The Cheque Buys
The price is the most interesting number. Rs 5,000 crore for 15 per cent implies a valuation of roughly Rs 33,300 crore. IIFL Finance closed at Rs 604.50 on 4 November, or about Rs 25,800 crore of market capitalisation on its 42.7 crore shares. The allotment therefore prices the company at a premium of close to 29 per cent, the sort of mark an incoming investor pays for a large primary issue and board influence rather than stock bought in the open market. The promoters’ Rs 1,200 crore is a dilution defence as much as a vote of confidence.
The numbers explain why both sides are moving now. Consolidated revenue for the September quarter was Rs 4,246 crore, up 28.5 per cent from Rs 3,305 crore a year earlier, and net profit more than doubled to Rs 766 crore from Rs 376 crore, lifting earnings per share to Rs 18 from Rs 8.86. Interest expense, however, climbed to Rs 1,909 crore from Rs 1,382 crore and provisions nearly halved to Rs 281 crore. Growth of this kind is funded with borrowed money, and equity is what breaks that loop.
Read more on newzshort:
Foreign Investors Return To India With Rs 38,971 Crore In A Week
From An RBI Freeze To A Capital Raise
IIFL Finance has spent two years repairing its reputation, which is why this raise reads as a rehabilitation story. On 4 March 2024 the Reserve Bank of India barred the company from sanctioning or disbursing gold loans, citing deviations in assay and purity checks on the metal it accepted as collateral, and the stock fell about 20 per cent. The curbs were lifted on 19 September 2024 after a special audit and remedial action, and the shares rose 13 per cent that day. The company runs one of the country’s larger gold loan networks, so capital is the constraint on regaining share.
Why Blackstone Wants In
Blackstone has run this playbook in India before. Its funds bought Aadhar Housing Finance from the DHFL promoters in 2019 and infused Rs 800 crore, listed the company in 2024, then launched a Rs 5,335 crore open offer for a 26 per cent stake in July 2025. Retail credit is the through line. IIFL Finance hands the firm a listed platform with a gold loan franchise, a home loan book and a branch network that would take years to build from scratch. The 29 per cent premium is the cost of entry, not a bargain price.
The Fairfax Question
The seller’s side matters just as much. Fairfax Financial, the Prem Watsa vehicle that has long been a large IIFL Finance shareholder, is working on an exit to fund its acquisition of IDBI Bank and, according to October reports, plans to fold Go Digit and IIFL Capital into the bank. Fairfax India sold Rs 374 crore of IIFL Finance shares in bulk deals on 30 July 2026. A large primary raise anchored by a marquee name gives the stock a way to absorb that overhang, which is why the board chose fresh capital over a plain block sale.
Risks And What To Watch
Three things can still go wrong. A 15 per cent stake in an NBFC needs the RBI’s prior approval, and the fit and proper test has held up such transactions before. The preferential allotment has to clear SEBI’s pricing rules and a shareholder vote, and the promoters’ Rs 1,200 crore will be read for how much of it is genuinely new money. The investment case also leans on firm gold prices while the home loan book scales. Watch the exchange filing that fixes the price and structure, the extraordinary general meeting notice, and third quarter loan growth.