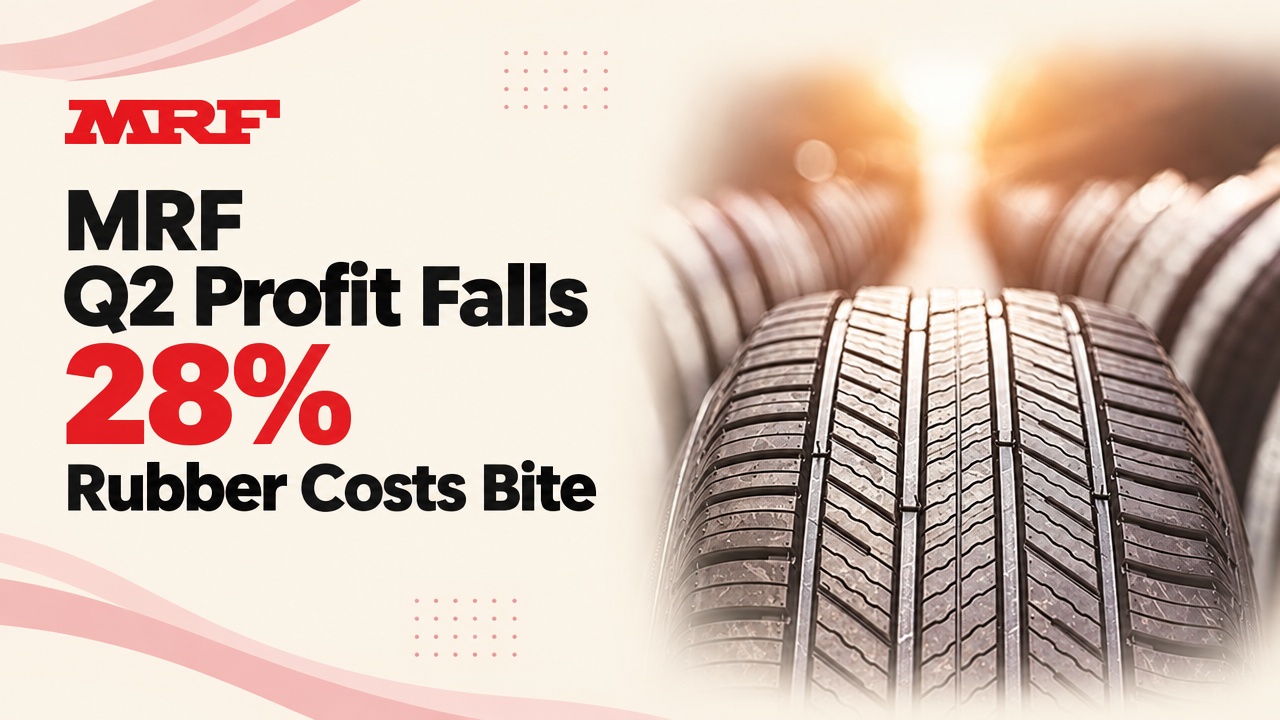

MRF’s standalone net profit fell 28 per cent to Rs 369 crore in the September quarter from Rs 512 crore a year earlier, as rubber and crude-linked costs overwhelmed record revenue.
Revenue from operations rose 17.6 per cent to Rs 8,524 crore from Rs 7,250 crore, the exchange filing showed. Total expenses climbed more than 22 per cent, so the gap between what MRF sold and what it spent widened to roughly four percentage points, and that gap is where the profit went. The exchanges were shut for Diwali-Balipratipada, so no share price moved on the result.
Read more on newzshort:
Honda Widens Lead Over Hero MotoCorp In October
The line item behind the gap is materials. Cost of materials consumed jumped about 44 per cent year on year, the sharpest rise in the accounts, per figures carried by Business Standard and Moneycontrol. Natural rubber stayed expensive through July to September as supply shortages and poor weather in producing countries held back output, while the war in West Asia raised the cost of crude derivatives used in tyres.
The arithmetic is stark. A net margin of 4.3 per cent on Rs 8,524 crore compares with 7.1 per cent a year ago, a contraction of about 270 basis points in one quarter. Volumes did not fail: MRF said tyre demand stayed resilient on steady dispatches from vehicle makers. Pricing power did. Consolidated accounts differ, and some reports put group net profit near Rs 417 crore, which is why headline declines ranged from 13 to 28 per cent. The standalone figures above are the ones Business Standard, Moneycontrol and NDTV Profit carried.
Read more on newzshort:
Hindalco Q2 Profit At Record Rs 7,532 Crore
Every Large Tyre Maker Is Bleeding
MRF’s decline is the mildest of the three listed tyre makers. CEAT, which reported on 14 October, posted a 40 per cent fall in net profit to Rs 112 crore even as revenue rose 26 per cent to Rs 4,762 crore. JK Tyre, on 23 October, saw net profit collapse 71 per cent to Rs 65.11 crore on revenue of Rs 4,850 crore, up 20 per cent.
Three double-digit revenue increases, three steep profit declines: that is a sector-wide input shock, not an execution problem at one firm. Each has raised prices. CEAT told CNBC-TV18 it expects a better second half on further hikes, a bet that rests on rubber cooling rather than demand accelerating.
A Rs 3 Dividend And A Deliberately Small Payout
The board declared an interim dividend of Rs 3 per share, 30 per cent on a face value of Rs 10, with 17 November as the record date. On a stock long known as India’s most expensive listed share, that is a token payout rather than an income event, and it fits MRF’s habit of retaining almost everything it earns to fund capacity. In a quarter when profit fell by more than a quarter, cash outranked distribution.
From Toy Balloons To India’s Largest Tyre Maker
MRF began in 1946 as a toy balloon unit run by K M Mammen Mappillai at Tiruvottiyur in Madras, moved into tread rubber in 1952 and into tyres in 1960, when Madras Rubber Factory was incorporated with help from Mansfield Tire and Rubber of Ohio. It went public in April 1961 and in 1967 became the first Indian company to export tyres to the United States.
Eight decades on it is India’s largest tyre maker, with ten plants across six states and a toys business, Funskool, started with Hasbro in 1987. That scale is what makes a 44 per cent jump in material costs so punishing: there is no small base left to absorb it.
The Editorial Read: A Rubber Cycle, Not A Verdict
Read this quarter as a commodity cycle, not a judgment on the franchise. Revenue grew 17.6 per cent and volumes held; what changed is the price of an input MRF cannot substitute. Tyre makers are price takers on rubber and slow price setters on their own product: a 5 per cent increase invites a rival to hold share. Relief will arrive the way it left: falling rubber prices reach margin faster than customers feel them. The risk is timing, since rubber supply takes years to replant and one good monsoon to recover.
What To Watch
Three data points matter from here. The first is the RSS-4 rubber price at Kottayam, the benchmark traders quote, and whether the new tapping season brings relief. The second is whether the increases CEAT and JK Tyre have announced hold through the December quarter without costing volume. The third is demand: Honda and Hero’s October dispatches show two-wheeler offtake holding up, which supports tyre volumes but stiffens vehicle makers on component prices. MRF’s December quarter will show whether September was the trough.