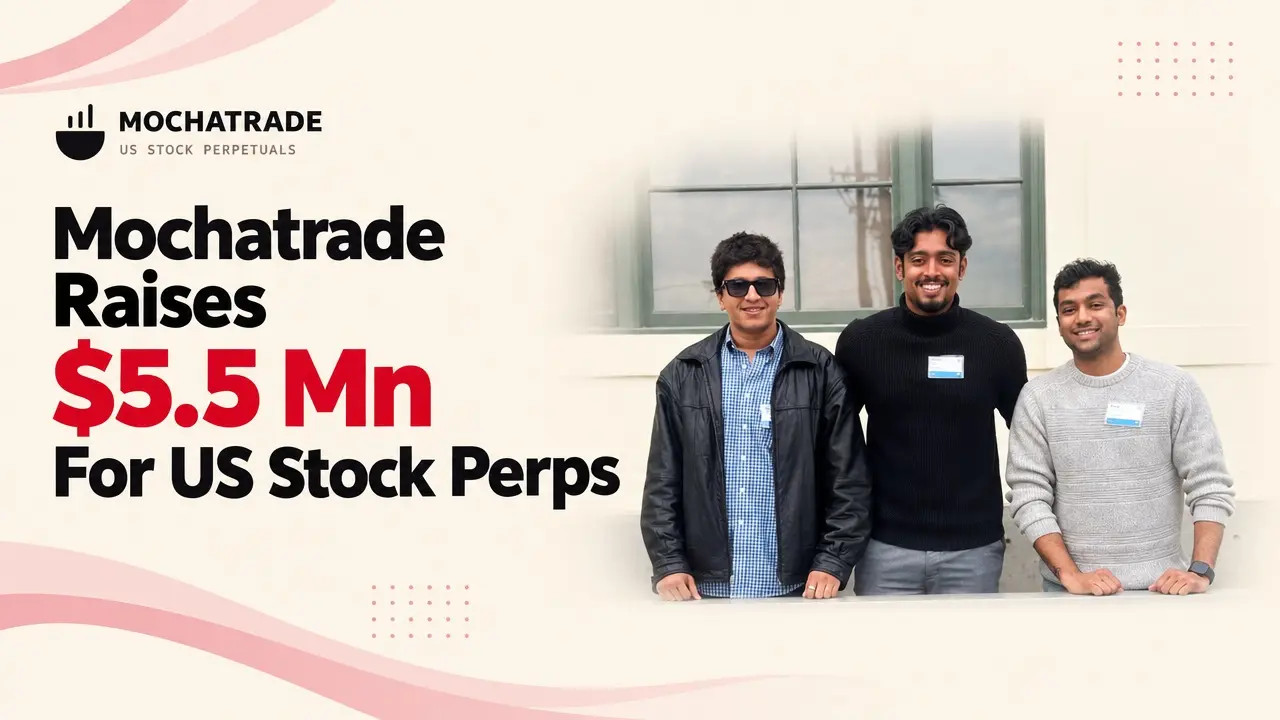

Mochatrade, a platform that lets Indian residents take positions on US stock prices without opening an American brokerage account, has raised $5.5 million, about Rs 52.3 crore, in a seed round led by CoinFund. Coinbase Ventures and Zero Knowledge Ventures general partner Nicky Montana joined the round announced on 27 October, with Y Combinator and Pioneer Fund already on the cap table.
The product is a perpetual futures contract tied to the price of a US stock rather than a share in it. Contracts carry no expiry, the trader never owns the underlying stock, and leverage runs up to 50 times. Accounts are funded through UPI, margins and profit and loss show in rupees, and users can bet on Tesla, Nvidia, Apple, oil, gold and silver. The beta has a waitlist past 25,000 sign ups.
Read more on newzshort:
Zerodha Opens US Stock Investing On Kite With 2,000 Companies
The Round And The Founders
Mochatrade puts total funding at $5.56 million including earlier money, Indian Startup News reported, so the $5.5 million headline is the new tranche rather than lifetime capital. Chetan Manda, the chief product officer, told The Block that revenue comes from trading fees and no token is planned. The cash goes into the trading engine, risk infrastructure and reaching active traders.
Founded in 2026, the company came out of Y Combinator’s Spring 2026 batch with 11 full time employees across New York and Bengaluru. Chief executive Utkarsh Sinha built the crypto wallet Martian, which crossed 2 million installs and about $2 billion of volume before it was acquired. Manda was director of product at Sprinklr, and Parth Maheshwari, the chief technology officer, worked on Photoshop for the web at Adobe.
Read more on newzshort:
Cent Raises $15 Million Series A Led By Blume
Why Indian Money Is Looking Overseas
Reserve Bank of India data quoted by Inc42 shows residents remitted $2.65 billion overseas for equity and debt investment in FY26, against $1.51 billion in FY24. The flow reached $1.4 billion between April and July of FY27, with July alone at $344.6 million, a 121 per cent jump. Those figures cover all overseas equity and debt purchases, not US stocks alone.
What Mochatrade sells against is friction. A traditional route has to work inside the Liberalised Remittance Scheme, capped at $250,000 per person per financial year, and absorbs 20 per cent tax collected at source on remittances above Rs 10 lakh, before dollar conversion and a foreign brokerage account. Sinha put India’s options premium turnover at $1.9 trillion last year.
The SEBI Squeeze At Home
The timing is not accidental. The Securities and Exchange Board of India has spent two years tightening equity derivatives, restricting weekly expiries to one benchmark index per exchange, raising contract sizes and lifting margin requirements. Those steps cut volumes and weighed on FY26 revenue at brokers including Zerodha and Groww. The field then splits in two, with Zerodha selling regulated, unleveraged US share ownership and Mochatrade selling levered exposure without ownership.
The Licence Question
Mochatrade’s Indian entity is registered with the Financial Intelligence Unit as a Virtual Digital Asset Service Provider and a reporting entity under the anti money laundering framework. The Economic Times noted that the registration covers reporting obligations and should not be read as approval of every product the company offers or plans to launch. There is no SEBI authorisation for these contracts.
Leverage is the first risk. At 50 times, a 2 per cent move against a position erases the margin behind it, and perpetual contracts carry a funding rate that drains a position held too long. Holders own no shares, collect no dividend and hold no claim on the company, while custody sits with an offshore venue. Pre IPO contracts and US stock options still need approvals it has not obtained.
What To Watch
Three things matter from here. Whether the beta converts 25,000 sign ups into funded accounts, because fee revenue only exists on the far side of that gap. Whether SEBI, the RBI or the FIU clarifies how stock linked perpetuals sit inside Indian law. And why a crypto native investor set led the round for a product with no token.
The editorial read is that Mochatrade has found a real gap and is standing in the least protected part of it. Demand for US exposure is documented and rupee settlement removes the friction retail traders mention most. None of that settles the licence problem, and a business whose growth depends on a regulatory classification holding can be repriced overnight by a circular rather than by a competitor.