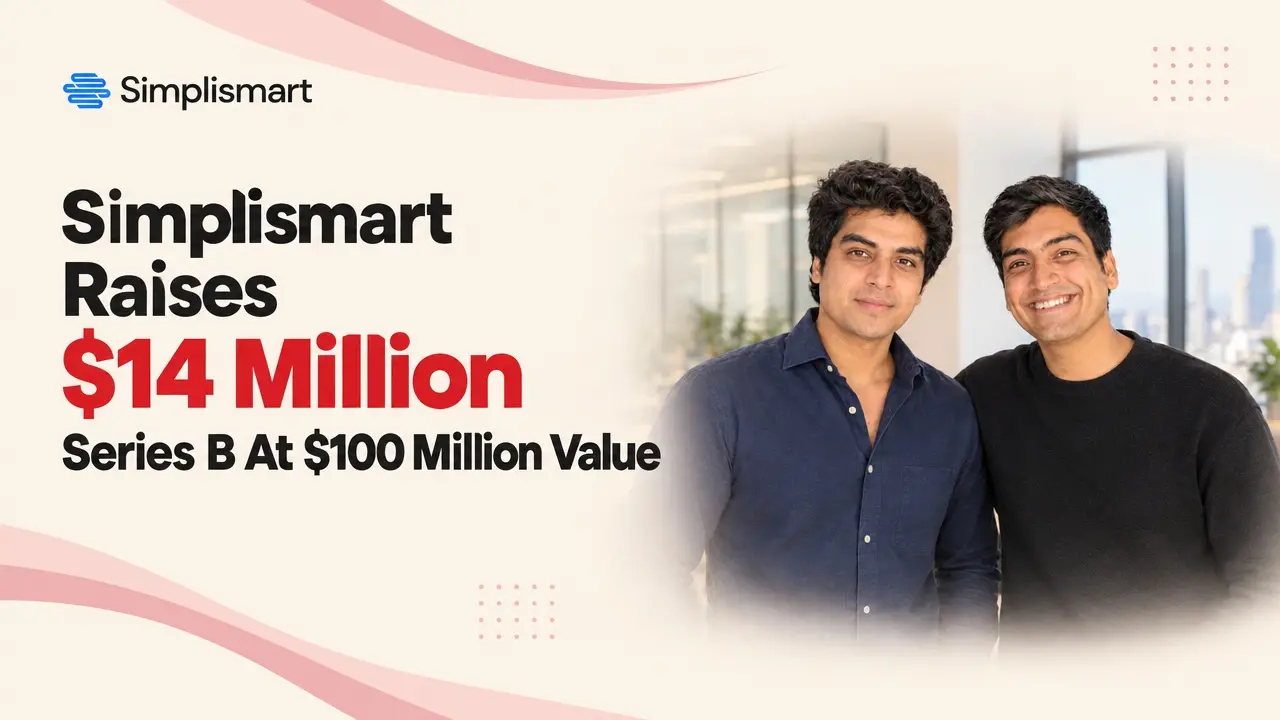

Simplismart, a Bengaluru startup that sells software for running AI models on existing graphics chips, has raised $14 million in a Series B round led by Dallas Venture Capital, with Nvidia joining as an investor. The all-primary round, announced on 27 October, values the four-year-old company at about $100 million after the money.
The company sells neither chips nor data centre space. It sells the layer in between: an inference engine that sets how a model should run, and an orchestration platform that deploys and scales it across a customer’s own cloud, its premises or Simplismart’s hosted service.
Read more on newzshort:
Enterprise AI Startup AuxoAI Raises $20.7 Mn Series A Led By NTTVC
What The New Money Buys
Chief executive Amritanshu Jain said the money goes into the inference engine and orchestration platform, a wider network of cloud partners that resell the software under their own brands, and sales hiring in North America. Part of it funds a scheduling layer that matches workloads with free GPU capacity across regions.
Simplismart is betting on distribution rather than data centres. It works with cloud operators that want to sell managed AI services without writing the software, including India’s Yotta, whose Shakti Studio runs serverless inference on its stack. Talks are also under way with operators and sovereign AI programmes in the Middle East, Australia and East Asia.
Read more on newzshort:
Sequoia-Backed Chip Startup Nuvacore Raising Funds at About 2.5 Billion Dollar Valuation
The Numbers Inside The Deal
At a $100 million post-money valuation the $14 million cheque is roughly 14 per cent of the company, and total funding stands at about $21 million. The $7 million Series A in October 2024 was led by Accel, with Shastra VC, Titan Capital and Notion co-founder Akshay Kothari among the investors; before that the founders had raised under $1 million.
Revenue is compounding faster than headcount. Jain said the annualised run rate has grown 14-fold in six months to an eight-figure sum, measured from recent customer usage rather than signed contracts and excluding money passed through to infrastructure providers. Over half of revenue comes from the United States, though India has more customers. The company employs 58 people.
Why Inference Is The Fight Now
Training a model is a one-time cost. Serving it is a monthly bill, which is why software between a model and a GPU is now a market of its own. Simplismart’s pitch is that buyers do not want the fastest or the cheapest configuration, they want one tuned to the application. For enterprise AI firm Ema it turned a target of 200 milliseconds at 9 cents per million tokens into 180 milliseconds at 7 cents.
Customers give that pitch a hearing. AI video companies InVideo, HeyGen and Higgsfield run on the platform, and Simplismart says it cut GPU serving costs at InVideo by 56 per cent. Providers that reserve GPU capacity and resell it carry the risk of idle hardware. Simplismart does not.
A Round Smaller Than The Street Expected
The closing number is well below what the market expected. The Economic Times had reported that Simplismart was in talks to raise $40 million to $50 million at a $300 million to $400 million valuation. Asked about that report, Jain declined to comment, said the company was not actively fundraising, and added that this Series B is closed.
Read as analysis, the gap between the rumour and the signed term sheet is the useful signal. A company that could have taken three times the money at three times the valuation took a smaller, all-primary cheque that leaves the cap table clean and the next round open. For a business whose revenue is measured on usage, that is the conservative choice.
The Nvidia Paradox
Nvidia’s participation looks odd, since it is backing software whose selling point is that some workloads need fewer of its chips. The logic reverses once the installed base is the asset. Simplismart’s engineers work with Nvidia’s solutions architects on integrations around Dynamo, its inference software, and Nvidia has introduced the startup to customers and partners.
The competitive set is uncomfortable. Simplismart sells against inference services from Nvidia itself, Amazon Web Services, Google Cloud and Microsoft Azure, each of which owns the silicon, the cloud and the customer relationship. Jain argues it wins where service agreements and total cost of ownership are tight, because it tunes a deployment instead of selling a preset tier.
What To Watch
Three things will decide whether this round reads cheap or expensive a year from now. The first is how much of the eight-figure run rate converts into contracted revenue, since usage-based revenue can fall as fast as it rises. The second is the partner count, which adds capacity without Simplismart spending on it. The third is the American mix.